DEEP DIVE
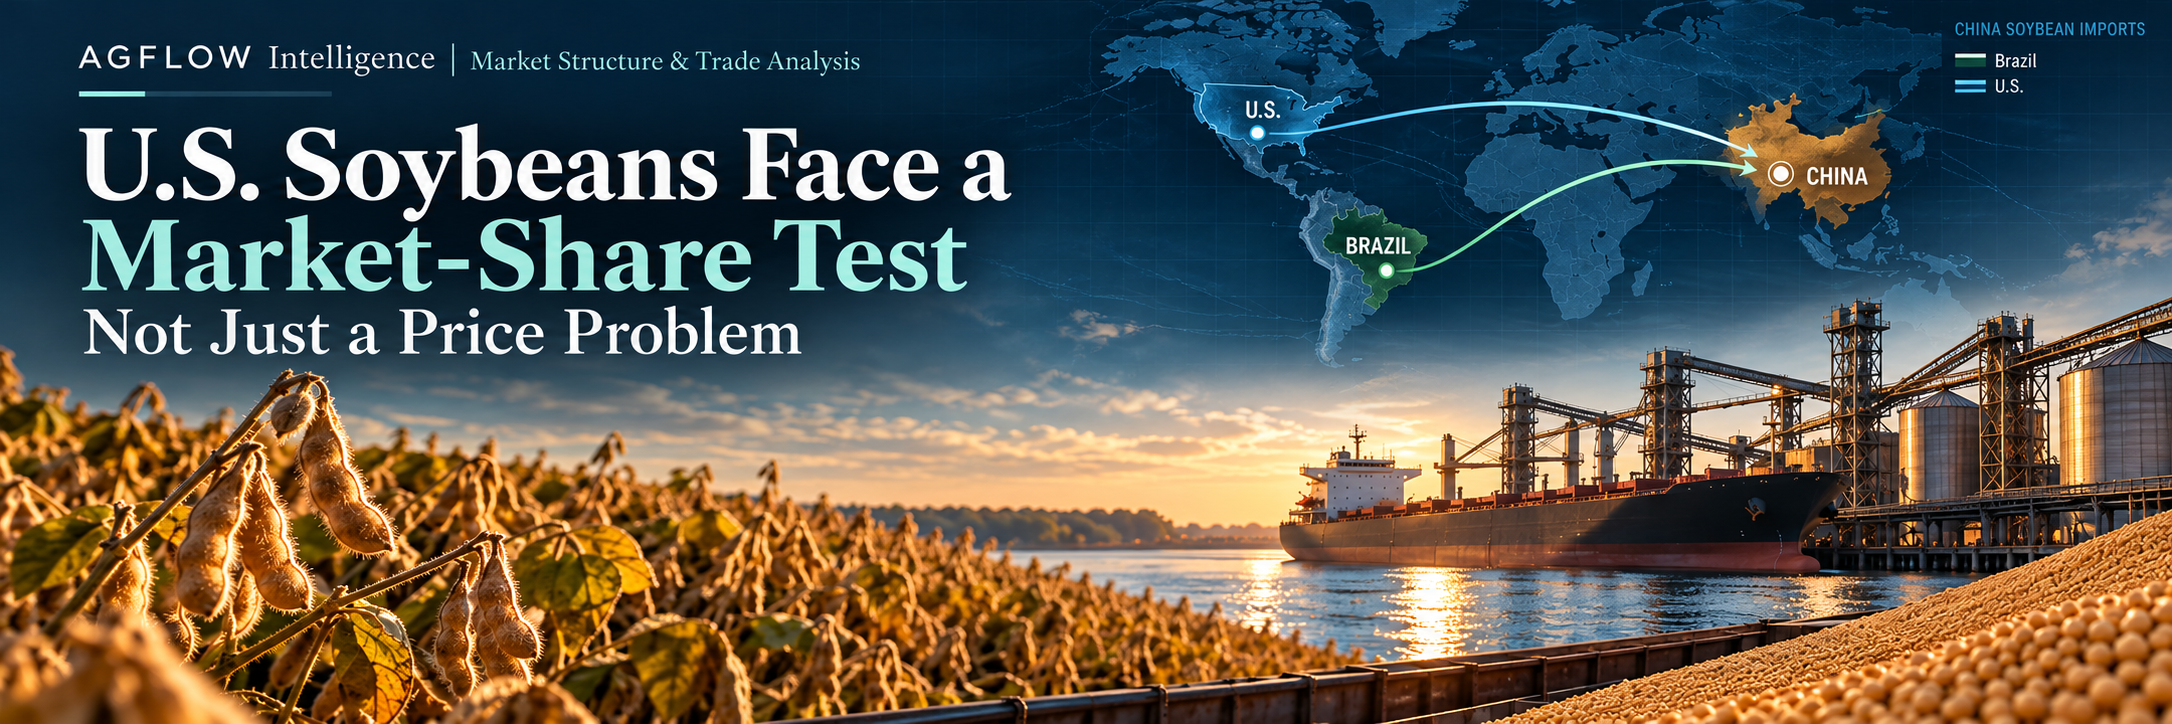
U.S. Soybeans Face a Market-Share Test — Not Just a Price Problem
Why China's shift toward Brazil raises a deeper question about American soybean competitiveness
The risk facing U.S. soybean exporters extends beyond the decline in Chinese purchasing commitments reported earlier this year. U.S. suppliers may also have to compete to recover procurement relationships they once took for granted.
Easing trade tensions could improve opportunities to compete, but it would not guarantee a return to historical purchasing patterns. Temporary trade diversion and durable supplier displacement are different commercial risks.
Reuters Breakingviews reported that China had booked approximately 12.4 million metric tons of U.S. soybeans as of July 2026 — 45% below the comparable year-earlier period. These figures describe purchasing commitments, not completed shipments, and do not establish China’s purchasing position in October.
For AGFLOW Intelligence, the central test is measurable: Is the United States losing a persistent share of China’s soybean imports, and is any displacement changing the economics of Gulf and interior basis, forward spreads, inventory movement, and domestic crushing?
Neither a decline in bookings nor a political announcement can establish a structural shift. That requires comparable origin-level import shares, shipment execution, delivered-price competitiveness, and confirmation in physical markets.
1. The Evidence: Significant Disruption, but Not Yet Proof of Permanent Loss
Bookings, export shipments, and Chinese customs arrivals describe different stages of the same trade system. A booked quantity is not necessarily a shipped or delivered quantity, and these measures should not be combined as though they were interchangeable.
Reuters' USDA-based chart reports a 76% decline in the nominal dollar value of U.S. soybean exports to China between calendar 2024 and 2025. USDA Foreign Agricultural Service commodity summaries separately list approximately $12.84 billion for China in 2024 and $3.00 billion in 2025.
The rounded figures independently corroborate a decline of roughly three-quarters in export value; they do not measure a comparable decline in physical soybean tonnage.
Neither the reported decline in bookings nor the decline in export value directly measures U.S. market-share erosion. Market share requires a denominator: China’s total soybean imports over the same observation period.
A proper assessment compares U.S.-origin soybean arrivals with China’s total soybean arrivals, using the same measurement period and physical-volume definition.
Reuters reports that substantial purchasing has shifted toward Brazil, but the cited figures do not independently quantify the percentage-point change in U.S. share of China’s soybean imports.
The evidence establishes significant trade disruption. The magnitude and permanence of structural market-share displacement require additional measurement.
2. The Competitive Risk: Losing Position in a Changing Procurement System
Soybeans are commodities, but international procurement is not determined by futures prices alone.
Importers evaluate delivered costs, freight availability, logistics, shipment reliability, financing arrangements, contract execution, and supply diversification.
When purchasing shifts toward another origin, commercial relationships can adapt.
Procurement schedules change. Freight programs are reorganized. Suppliers establish new relationships. Buyers gain operating experience with alternative origins.
Over time, these changes can make an alternative supplier more deeply integrated into the purchasing system.
That distinction separates two possible outcomes.
Temporary trade diversion occurs when purchasing shifts because of immediate price differences, trade restrictions, or logistical conditions.
Structural supplier displacement occurs when sourcing patterns remain materially changed even after the original disruption subsides.
Brazil's position in China's soybean procurement system makes the second possibility worth examining.
However, China routinely adjusts purchasing between U.S. and South American origins according to harvest cycles, availability, and relative delivered prices.
Brazilian export strength during its normal marketing window is not, by itself, evidence of permanent U.S. displacement.
A more convincing structural signal would be persistent U.S. market-share erosion across multiple comparable marketing seasons, including periods when American soybeans are competitively priced and readily available.
Where trade barriers ease, U.S. exporters gain an opportunity to compete; they do not automatically regain historical market share.
3. How Export Displacement Could Affect the U.S. Soybean System
At AGFLOW Intelligence, we evaluate soybean markets through Chicago futures, the forward curve, physical demand, basis relationships, and inventory ownership.
Sustained export displacement could affect these mechanisms, depending on how much of the lost demand is absorbed by other export destinations or domestic processors.
Chicago Futures: Expectations and Balance-Sheet Adjustment
If weaker exports reduce total U.S. soybean disappearance, ending stocks could rise, all else equal.
However, reduced Chinese purchasing does not necessarily imply an equivalent decline in total U.S. exports. Other destinations may absorb part of the displaced volume.
Futures also reflect production, global supply, domestic processing, expectations, and financial positioning.
Neither weaker Chinese bookings nor lower futures prices independently establishes structural demand deterioration.
Basis: Where Demand Becomes Local
If export demand weakens, Gulf bids and interior locations connected to export channels may experience reduced competition for physical soybeans.
Processor-oriented markets could remain comparatively firm where domestic crush demand is supportive.
The resulting divergence may reveal differences in regional demand conditions.
However, transportation economics, local supply, seasonal patterns, and logistical constraints must be considered before attributing basis weakness to export displacement.
Forward Curve: The Economics of Carrying Inventory
If weaker demand contributes to inventory accumulation, the market may offer greater incentives to defer movement through nearby-deferred futures spreads.
But wider carry is not proof of deteriorating demand.
Storage costs, interest rates, harvest pressure, and inventory distribution also influence calendar spreads.
The commercial question remains whether available carry adequately compensates the economic cost and risk of holding inventory.
Inventory Ownership: Supply Is Not the Same as Availability
Aggregate inventory levels do not determine immediate commercial availability.
Ownership, location, contractual commitments, financing, and selling behavior influence when soybeans enter the physical market.
Consequently, some locations may maintain firm cash bids even when the national supply balance appears comfortable.
The market prices not only how many soybeans exist, but also where they are, who controls them, and when they become available.
4. Can Domestic Crushing Absorb Displaced Export Supply?
Expanded domestic processing offers one potential mechanism for absorbing soybeans that might otherwise remain in the U.S. supply system following a reduction in export demand.
Additional soybean crushing can increase local demand, support regional procurement, and redirect some whole-bean supply into meal and oil production.
But installed crushing capacity does not automatically create profitable demand.
Processors must operate within commercially viable margins.
Their soybean meal and oil production must also find sufficient domestic or export markets.
If domestic crush increases while product demand remains supportive, part of the adjustment may occur through a change in the composition of U.S. agricultural exports.
Instead of exporting whole soybeans, the United States may export more processed soybean products.
However, that adjustment depends on actual crush utilization, margins, transportation economics, and meal and oil demand.
Nor does increased domestic processing necessarily compensate for the geographic consequences of weaker whole-bean exports.
Processors and export terminals compete for soybeans in different locations, under different logistical and commercial conditions.
Importantly, expanding domestic processing can offset part of the domestic balance-sheet impact of weaker exports, but it cannot restore the U.S. percentage share of China's soybean imports.
These are separate economic outcomes.
The relevant measure is economically sustainable processing demand — not announced or installed capacity alone.
5. How Would We Know if U.S. Market-Share Loss Is Becoming Structural?
The Reuters analysis raises an important question, but a structural conclusion requires more than one purchasing period.
AgFlow evaluates potential structural displacement through six complementary tests. Each isolates a different question; none is a stand-alone verdict.
1. U.S. Share of China's Total Soybean Imports
Measure: U.S.-origin soybean arrivals as a proportion of all Chinese soybean imports, using the same volume definition and observation period:
U.S. Market Share (%) = U.S.-Origin Soybean Imports into China ÷ Total Chinese Soybean Imports × 100
Interpret: Compare equivalent seasonal windows across multiple years. Do not substitute U.S. bookings or shipments for Chinese customs arrivals. The cited figures do not supply an origin-level import denominator, so no change in China's U.S.-origin market share is calculated here.
2. Delivered-Origin Competitiveness
Measure: Whether Chinese buyers continue to prefer Brazilian beans when U.S. offers are competitive on a comparable delivered-cost basis.
Interpret: Account for harvest windows, freight, exchange rates, tariffs, quality, and supply availability. Persistent preferences under genuinely comparable conditions would strengthen—but not establish—the structural-displacement hypothesis.
3. Export Commitments and Shipment Execution
Measure: Soybean commitments by destination alongside inspections, loadings, and completed shipments across comparable marketing periods.
Interpret: A booking is not an executed shipment. Persistent weakness in both contractual commitments and physical execution offers stronger evidence of demand impairment than a single purchasing period.
4. Gulf and Interior Basis Transmission
Measure: Gulf export-linked basis and connected interior bids relative to comparable seasonal relationships.
Interpret: Persistent weakness may indicate diminished export competition, but local supply, river logistics, transportation costs, and processor demand must be accounted for before drawing that conclusion.
5. Forward Spreads and Inventory Economics
Measure: Inventories versus seasonal norms, and nearby-deferred spreads relative to full storage and financing costs.
Interpret: Greater carry may encourage deferral of movement, but inventory accumulation or wider spreads cannot identify weaker exports as the cause without corroborating balance-sheet and demand evidence.
6. Domestic Processing Absorption
Measure: Realized crush throughput, economically sustainable processing margins, and markets for the resulting soybean meal and oil.
Interpret: Actual utilization and product demand—not announced capacity—determine how much whole-bean export displacement domestic processing can absorb. This does not restore the U.S. share of China's soybean imports.
The Confirmation Standard
Read these six indicators together across comparable marketing seasons: customs arrival shares test displacement, delivered-origin economics and export execution test persistence, and domestic physical indicators test commercial consequences.
These are research tests, not completed findings. Without consistent origin-level import volumes, a permanent loss of U.S. market share remains unproven.
6. What This Means for Producers and Merchandisers
The greatest commercial mistake would be to turn a geopolitical expectation into an automatic merchandising decision.
A trade agreement is not an executed export sale.
An announced purchase is not a completed shipment.
And expectations of stronger demand do not automatically justify storing soybeans.
For producers, the decision remains whether the market is offering sufficient compensation to sell, store, hedge, or defer pricing.
For merchandisers, the priorities remain execution margins, basis exposure, physical supply access, inventory financing, and contractual risk.
A recovery in Chinese purchasing could improve export-linked demand and change regional merchandising incentives.
Persistent displacement could produce a different adjustment, potentially increasing the importance of domestic processing and alternative export destinations.
The objective is not to predict which political scenario will occur. It is to measure how the commercial soybean system responds to the demand conditions actually present.
Final Perspective: Market Share Cannot Be Taken for Granted
Global soybean demand can remain substantial even if the United States captures a smaller share of China’s imports. The magnitude and persistence of any shift must be measured through comparable origin-level data — not inferred from one booking period.
The domestic economic consequences are a separate question. Gulf and interior basis, futures spreads, inventory behavior, and domestic processing can reveal how changes in export demand affect the commercial system, but none is conclusive in isolation.
Three tests therefore remain distinct: Are purchasing commitments translating into U.S. shipments? Is the U.S. share of China’s imports changing across comparable seasons? And is any displacement altering the economics of the domestic soybean market?
U.S. exporters must compete on delivered cost, logistics, reliability, and contract execution. Improved trade relations may help, but they cannot guarantee a return to prior purchasing patterns.
For producers and merchandisers, the priority is not predicting a political outcome. It is determining what current futures, basis, spreads, physical demand, and inventory costs justify in selling, storing, hedging, and pricing.
Leo Rocha
Founder & Head of Research
AGFLOW Intelligence
Independent soybean market intelligence focused on futures, forward curves, physical demand, basis, inventory ownership, and commercial decision-making.
Explore our research and subscribe to the free weekly AgFlow Soybean Market Signal:
https://www.agflowintelligence.com/
Sources Used in This Article
Gabriel Rubin, Reuters Breakingviews, October 8, 2026. US farmers are past the point of political return.
https://www.breakingviews.com/columns/considered-view/us-farmers-are-past-point-political-return-2026-10-08/
USDA Foreign Agricultural Service, Soybeans commodity export data, calendar 2024 and 2025, China destination (nominal U.S. export values).
https://fas.usda.gov/data/commodities/soybeans
Data Sources for Future Monitoring (Not Used to Calculate Market Share)
USDA Foreign Agricultural Service, Export Sales Query System (weekly commitments, outstanding sales, and accumulated exports).
https://fas.usda.gov/data/databases-applications
General Administration of Customs of China, official customs statistics query (commodity arrivals by country of origin; required to calculate Chinese import-origin share).
https://stats.customs.gov.cn/
Research note: Reuters supplies the July 2026 bookings comparison and the 76% export-value chart figure. USDA FAS commodity tables corroborate the approximate nominal export-value decline. Export sales and Chinese customs resources are listed for future monitoring only; this paper did not calculate origin-level import market share. AgFlow’s six indicators are diagnostic tests, not proof of permanent displacement.