DEEP DIVE
United States Soybean Supply Demand and Price Outlook for 2026/2027
Record Production Meets Faster Demand Growth
USDA projects a record 4.535 billion bushel soybean crop for 2026/27, yet it also projects lower ending stocks, a stocks to use ratio below 7 percent, and a higher season average farm price. The balance sheet tightens because total use grows faster than supply. Domestic crushing provides most of the structural demand growth, while the export forecast supplies the marginal change that reduced the latest carryout estimate. Globally, the soybean stocks-to-use ratio also declines, from 29.09 percent in 2025/26 to 28.03 percent in 2026/27, although inventories remain unevenly distributed. Illinois farm price seasonality offers timing context, but its wide variation across years leaves the storage decision dependent on local bids and costs.
The 2026 27 BalanceSheet at a Glance
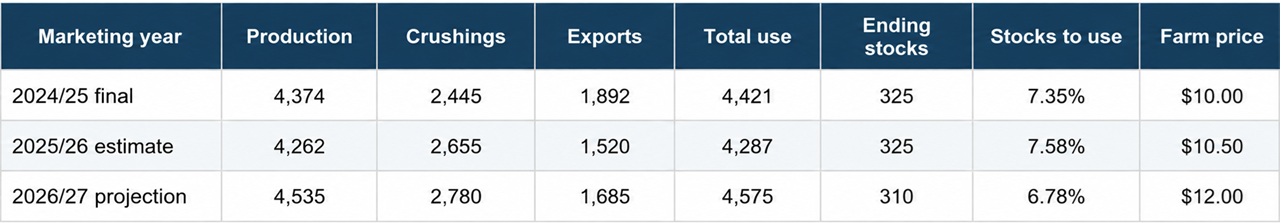
Source: USDAWASDE 675, September 11, 2026. Million bushels except stocks to use and farmprice; stocks to use ratios are calculated.
Record Production MeetsFaster Demand Growth
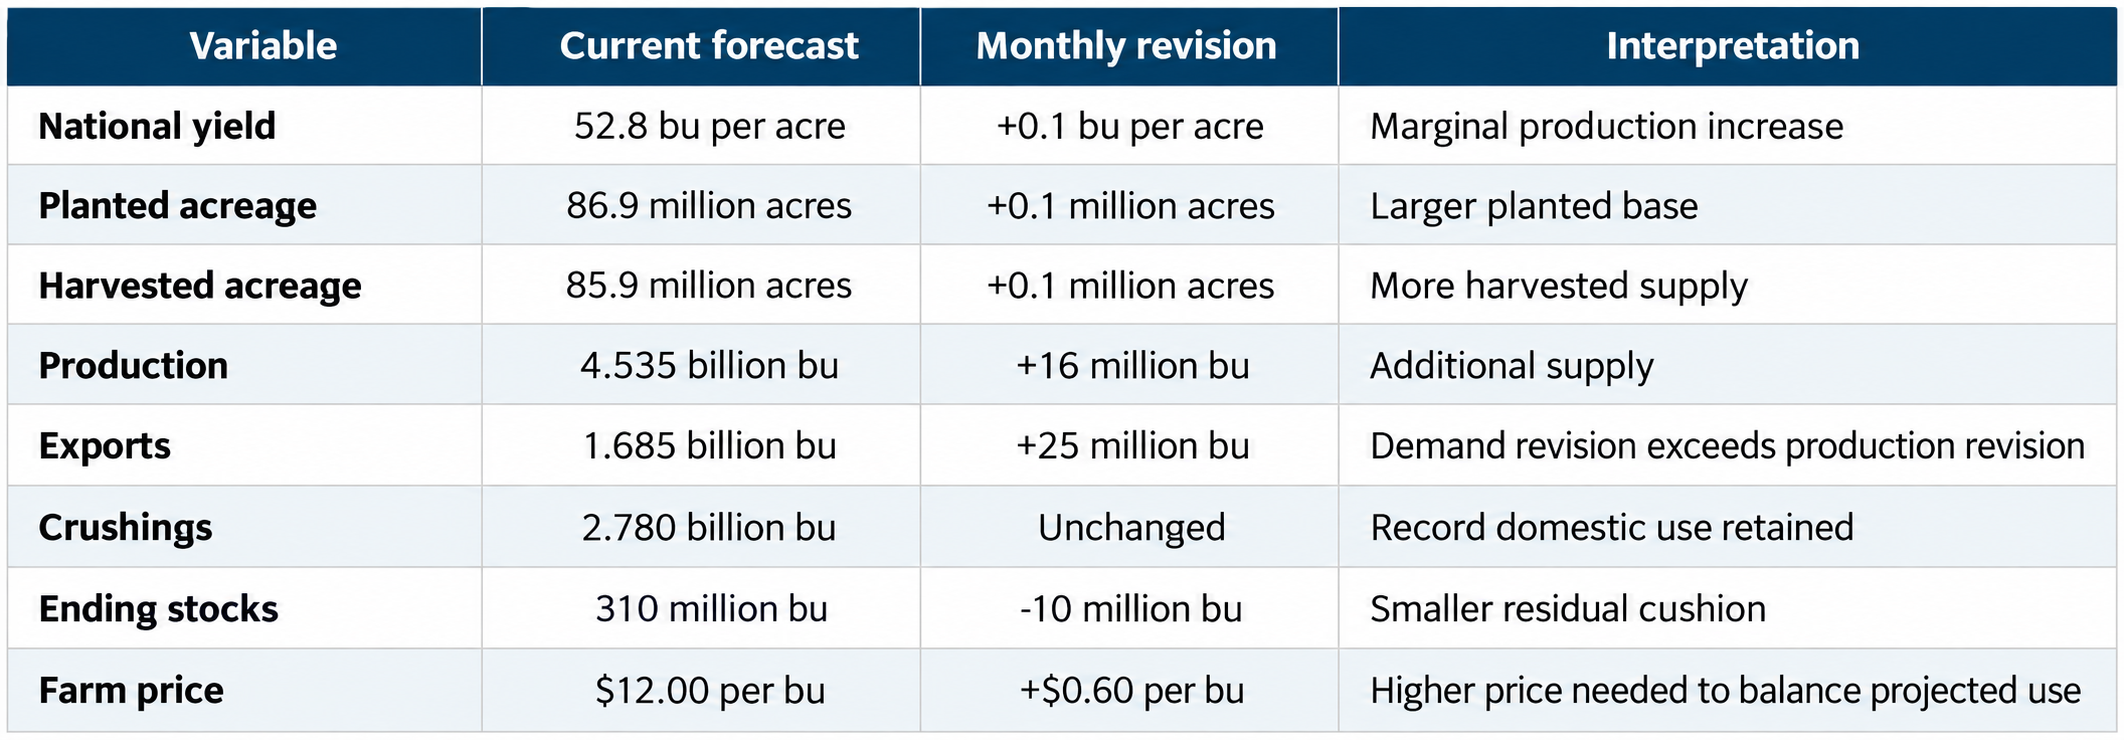
The 2026/27 production projection is 273 million bushelsabove 2025/26, an increase of 6.4 percent. It also exceeds the previous final record of 4.465 billion bushels in 2021/22 by 70 million bushels. Acreage and yield both contribute. USDA raised planted acreage to 86.9 million acres, harvested acreage to 85.9 million, and the national average yield to 52.8 bushels per acre.
The larger crop does not create a larger carryout because total use rises by 288 million bushels. Production grows by 273 million, so projected disappearance exceeds the increase in supply by 15 million bushels. Ending stocks fall from 325 million to 310 million bushels. The market therefore enters the forecast year with more production but a smaller residual inventory cushion.

Figure 1 U.S. soybean production, crushings, and exports from 2014/15 through the2026/27 projection
Note: Crushingsand exports are stacked demand channels, not a complete allocation ofproduction. Seed and residual use are excluded, and total use can draw onbeginning stocks.
Domestic Crushing Is theMain Demand Engine
Crushings are projected at 2.780 billion bushels in 2026/27, up 125 million from 2025/26 and 335 million from the 2024/25 final estimate. Over the same two year span, production increases by 161 million bushels. Crushing growth therefore exceeds production growth by 174 million bushels, showing how rapidly the domestic processing channel is expanding relative to the crop.
Exports recover to 1.685 billion bushels after dropping to 1.520 billion in 2025/26. The recovery is meaningful, but the projected volume remains 25.6 percent below the 2.266 billion bushel peak recorded in 2020/21. Exports would equal roughly 37 percent of 2026/27 production, compared with about 43 percent across the completed 2000/01 through 2024/25 period.
This demand mix changes where confirmation should appear. A balance sheet led by crushing should transmit through processor bids, regional basis, soybean meal and oil values, and actual monthly crush volumes. Export sales and inspections remain important, but they are no longer the only large channel capable of tightening the balance sheet.
Why the Latest MonthlyRevision Tightened the Outlook
The arithmetic explains the counterintuitive result. USDA added 16 million bushels to production, 25 million to exports, and 1 million to residual use. Use therefore increased by 26 million bushels while supply increased by 16 million, reducing ending stocks by exactly 10 million bushels. The higher price forecast is consistent with a tighter residual balance, eventhough the crop itself grew.
Figure 2 Projected percentage change from 2025/26 to 2026/27
Stocks to Use MovesBelow Seven Percent
Projected ending stocks of 310 million bushels divided by total use of 4.575 billion produce a stocks to use ratio of 6.78 percent. That is 0.80 percentage point below the 2025/26 estimate and 1.31 points below the 8.09 percent average for completed marketing years from 2000/01 through 2024/25.
A 6.78 percent ratio is tight, but it does not establish structural scarcity. The series reached 2.65 percent in 2013/14 and remained near 4.5 percent in several other tight years. The current projection provides less room for a demand surprise or production revision, but it does not imply that physical supply is unavailable.
Figure 3 U.S. soybean stocks to use and average farm price from 2000/01 through the 2026/27 projection
Farm Prices Respond tothe Residual Balance
USDA raised the 2026/27 season average farm price forecast to $12.00 per bushel. That is $1.50 above 2025/26, a 14.3 percent increase, and about 13.7 percent above the average for the latest ten completed marketing years. It remains below the nominal peaks of $14.40 in 2012/13 and $14.20 in2022/23.
Across the completed 2000/01 through 2024/25 period, the correlation between the national farm price and stocks to use is -0.40. The correlation between annual percentage changes is approximately -0.52. These results support an inverse relationship, but they do not make stocks to use a complete pricing model. Inflation, crop expectations, export timing, crush margins, futures positioning, basis, and the broader oilseed complex also influence the price received during the marketing year.
Illinois Prices Providea Consistent Regional Check
Illinois seasonal average farm prices track the national series closely. The correlation is 0.999 across 25 completed marketing years in the supplied Illinois workbook and the USDA national series, and Illinois averaged about $0.20 per bushel above the national price. The Illinois relationship with stocks to use is nearly identical to the national result at-0.40.
For 2025/26, the Illinois monthly prices received fromSeptember 2025 through July 2026 average $10.94 per bushel on a simple, unweighted basis, up from $10.31 for September through January alone. The June observation is $11.60 and July is $11.80. August has not yet been published. The 11-month average is not an official Illinois seasonal average, and its difference from the $10.50 national forecast cannot be treated as an Illinois premium: the national seasonal price reflects the timing and volume of producer marketings, while this simple average does not.

Pearson correlations use the 25 completed marketing years from 2000/01 through 2024/25. Historical national prices, stocks, production, exports, and crushings come from the USDA ERS Oil Crops Yearbook, Table 3, updated March 2026; Illinois seasonal prices come from the supplied Illinois workbook. Correlation describes association, not causation; common trends raise some level correlations.
Illinois Farm Price Seasonality
To compare crop years across decades, each Illinois marketing year is indexed to its September average price(September = 100). In the 20 completed years from 2005/06 through 2024/25, the median stands at 102.9 in June but finishes at 99.5 in August. The 1960/61–2024/25 median ends at 102.0. These paths describe historical medians, not a price target for 2026/27.

Figure 4 Illinois farm price paths indexed to September across completedmarketing years
The direction changes month by month. From November to December, the Illinois monthly average rose in 16 of the 20 recent completed seasons. It rose from July to August in only six. A higher monthly average does not establish a profitable storage return because the frequency excludes the size of the move and the cost of waiting.

Figure 5 Frequency of higher Illinois farm prices in the following month,2005/06–2024/25

Selected transitions from the 20-year sample. Ties count as no increase.
Source: supplied Illinois monthly average farm prices received; AgFlow calculations.
Individual marketing years differ sharply. In 2007/08, the June monthly average was about 73% above that September; in 2023/24 it was about 10% below. The heatmap shows each year against its own September price and excludes incomplete 2025/26 observations.

Figure 6 Changein Illinois farm prices from September by marketing year
Commercial reading: these are statewide monthly prices received by farmers, not Chicago futures or executable forward bids. Before storing or delaying a sale, compare the available local cash and deferred bids with basis, futures carry, financing, storage, shrink, and delivery costs. Seasonal history by itself does not authorize a hold or escalation.
Historical BenchmarksClarify the Forecast

Sources: USDA ERS Oil Crops Yearbook, Table 3 (March 2026); supplied Illinois soybean prices workbook; and USDA WASDE 675 (September 2026). AgFlow Intelligence calculations.
Global Soybean Stocks to Use Also Declines
USDA projects global soybean ending stocks of 124.02 million metric tons against 442.44 million tons of domestic use in 2026/27. Dividing stocks by use gives 28.03 percent, down from 29.09 percent in 2025/26 and 30.56 percent in 2024/25. Global production rises to 442.35 million tons, while the projected ending inventory cushion narrows. The world table is assembled across differing local marketing years, so changes in its aggregate stocks should not be reduced to a single production-minus-use calculation.

Source: USDA WASDE 675, World Soybean Supply and Use, September 11, 2026, p. 28. Million metric tons; ratios calculated by AgFlow Intelligence as ending stocks divided by domestic total use. 2024/25 is historical, 2025/26 is estimated, and 2026/27 is projected.
The longer series puts the two-year decline in context. In theworkbook's 27 completed years from 1998/99 through 2024/25, 22 had a lower world stocks-to-use ratio than the 28.03 percent projected for 2026/27. Theratio is down 2.53 percentage points from 2024/25, but the projected global inventory cushion is still above most observations in this series.
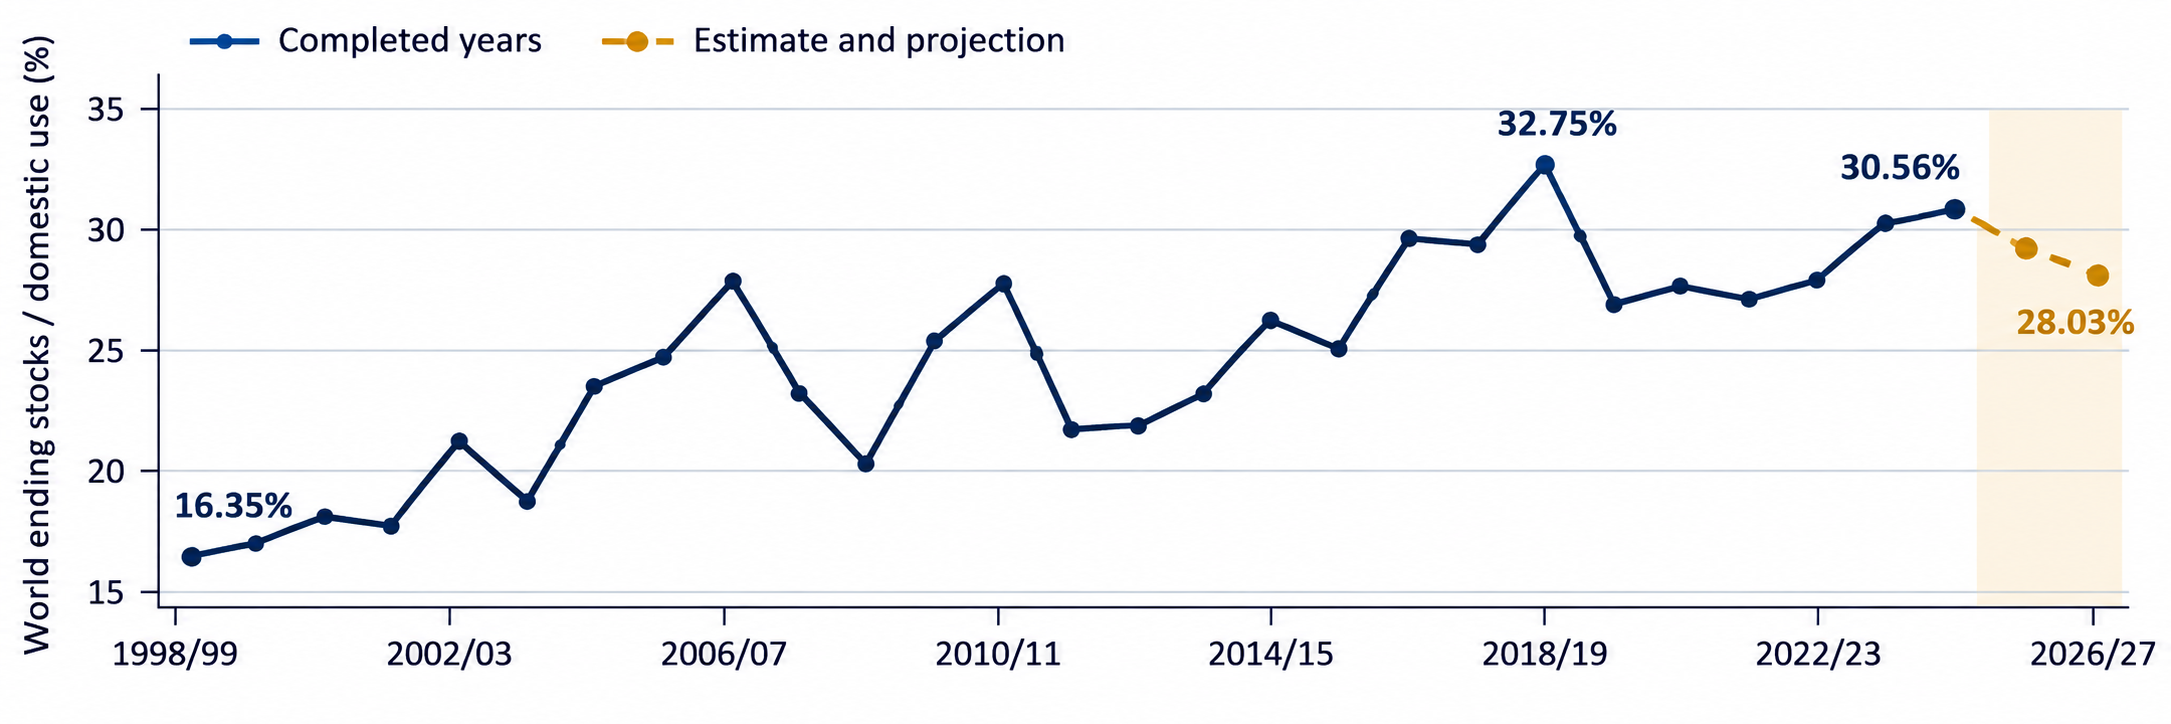
Line chart source: USDA WASDE World Soybean Supply and Use; the supplied workbook selects the latest available estimate for each year from its December 2000–2025 and September 2026 report editions. The dashed segment contains the 2025/26 estimate and 2026/27 projection.
Outside China, stocks to use fall from 27.27 percent in 2025/26 to 26.03 percent in 2026/27. China holds 44.26 million tons, or about 35.7 percent of projected global ending stocks. Its inventories are therefore a material part of the world ratio, but they are not automatically available to other importers. The global decline supports the direction of the U.S. tightening signal without confirming scarcity or replacing evidence from U.S. export flow and cash markets.
Method note: The world ratio uses global domestic total use from the WASDE world table. The U.S. ratio elsewhere in this report uses U.S. total use, including exports. Their levels are not directly comparable; compare each ratio with its own history. USDA notes that world imports and exports may differ because national marketing years and reporting lags do not align.
Global Oilseed SupplyTempers the Signal
The U.S. soybean balance sheet is constructive, but the global vegetable oil setting is mixed. USDA raised 2026/27 rapeseed production by 1.9 million metric tons and sunflowerseed production by 1.0 million metric tons. The resulting increase in rapeseed and sunflowerseed oil supply more than offsets the lower Indonesian palm oil forecast in USDA's oilseed outlook.
Additional competing oil supply can limit how much strength passes through soybean oil into soybean values. At the same time, strong global vegetable oil demand supports higher rapeseed and sunflowerseed crush forecasts. The external signal is therefore supportive of processing volume butless conclusive for outright soybean oil price escalation.
What the ForecastRequires from the Physical Market
The latest 2025/26 estimate remains the near-final baseline at 325 million bushels of ending stocks and 7.58 percent stocks to use, near but still above AgFlow's 7.5 percent escalation reference. The 2026/27 current marketing-year projection is a non-authoritative overlay that identifies a tighter potential state; it does not prove that projected demand will occur. Confirmation should develop in observable physical channels before the forward balance sheet carries execution authority.
· Export sales and shipments must develop fast enough tosupport the 1.685 billion bushel forecast.
· Monthly crush volumes, processor basis, and crushmargins must remain consistent with 2.780 billion bushels of domesticprocessing.
· Regional basis should strengthen where processors orexporters need ownership rather than remain isolated to a few delivery points.
· The futures curve should become less willing to payfor storage if nearby ownership becomes more valuable.
A failure in any one channel does not automatically invalidate the outlook. A sustained failure across exports, crush, basis, and spreads would. That distinction matters because the 2026/27 balance sheet has less room for forecast error, but it still depends on projected demand.
Implications forProducers
The record crop should not be used by itself as a reason to expect lower prices. The same is true in reverse: a 6.78 percent stocks to use ratio should not be used by itself as a reason to hold grain for a higher price. The commercial decision still depends on the local cash bid, basis, available carry, storage cost, financing cost, and delivery alternatives.
For stored soybeans, the relevant question is whether the forward curve and local basis pay the full cost of waiting. For unpriced production, the tighter forward balance supports preserving some upside participation, but it does not remove the need to price incrementally when delivered cash bids are attractive. The balance sheet informs the decision; it does not replace the execution test.
FinalAssessment
FORWARD TIGHTENING / DEMAND ABSORPTION / NOT SCARCITYCONFIRMATION
The 2026/27 outlook combines record production with as maller ending inventory cushion. Total use rises faster than production, domestic crushing sets another record, and the latest export revision absorbs more than the incremental crop. Those changes reduce projected ending stocks to 310 million bushels and lower stocks to use to 6.78 percent. The global soybean ratio declines to 28.03 percent, with the ratio outside China at 26.03 percent; both reinforce the direction of tightening while leaving the U.S. physical confirmation test intact.
The constructive price implication is conditional. The 2026/27 current-year projection overlay has no escalation authority on its own. Export flow, processing demand, basis, and spreads must confirm that projected tightening is moving through the physical system. Until then, the outlook supports participation and selective pricing rather than an aggressive scarcity posture.

AgFlow decision framework applied to USDA balance sheet estimates and projections, with physical confirmation requirements.
Sources and Method
Sources: USDA WASDE 675 (September 11, 2026); USDA NASS Crop Production and Agricultural Prices (Illinois monthly prices through July 2026); USDA ERS Oil Crops Outlook and Oil Crops Yearbook, Table 3 (March 2026); supplied Illinois soybean prices workbook (monthly prices and completedseasonal averages). Historical U.S. prices and supply/use for 2000/01–2024/25 use the yearbook; latest balance sheets use September WASDE. World and world-less-China ratios divide ending stocks by domestic use; the U.S. ratio uses total use, including exports. Compare each ratio with its own history. Statistics and Pearson correlations are AgFlow calculations. The 2025/26 national values are estimates, while 2026/27 values are projections. The2025/26 Illinois $10.94 is the unweighted mean of 11 monthly prices, not an official seasonal average; August was unavailable as of September 24, 2026. The incomplete year is excluded from historical correlations.